



Here’s a depressing stat: a large share of college students say they feel stressed about money more than about exams. And most of them have never been taught how to budget — not in school, not at home, nowhere. So money arrives, money evaporates, and the month ends with instant noodles and regret.
The 50/30/20 rule is the simplest budgeting system that actually works, and it was popularized by Senator Elizabeth Warren in her book All Your Worth. No spreadsheets the size of a thesis. No guilt. Just three buckets and one rule of thumb. Here’s how it works for a student budget.
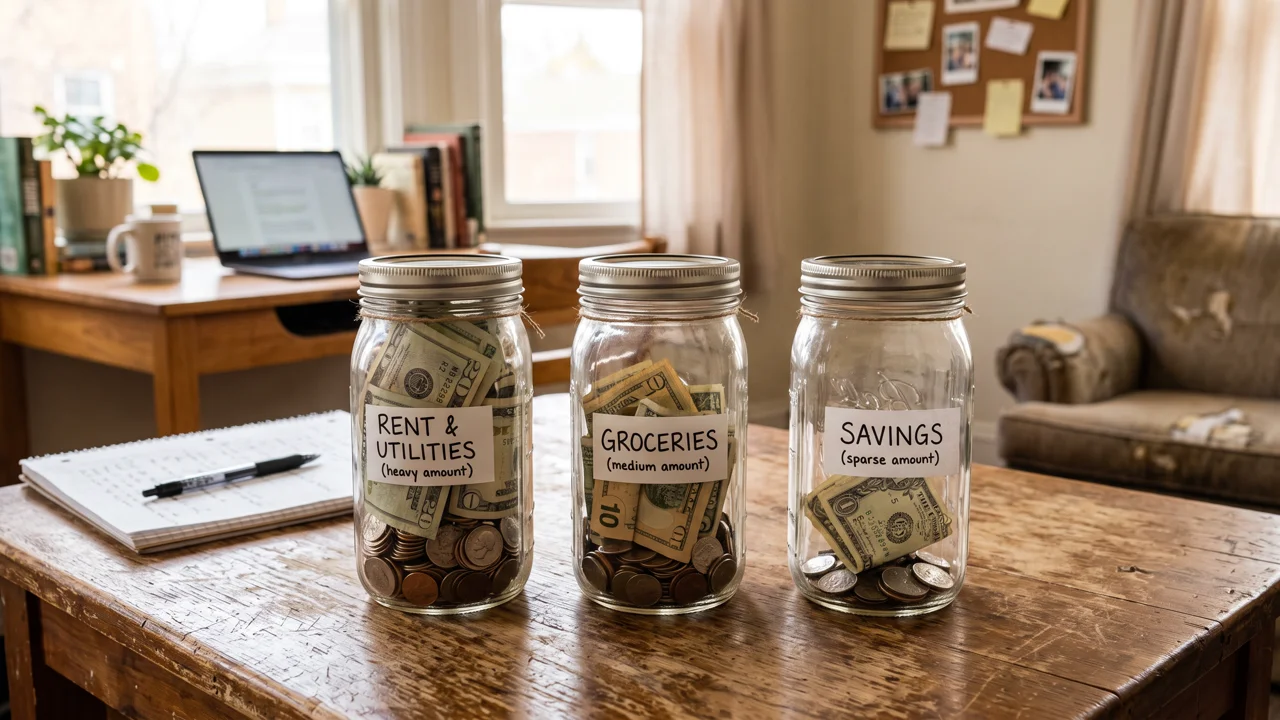
The Three Buckets, Explained
Take your total monthly income — job, allowance, stipend, side gigs, all of it, after taxes — and split it like this:
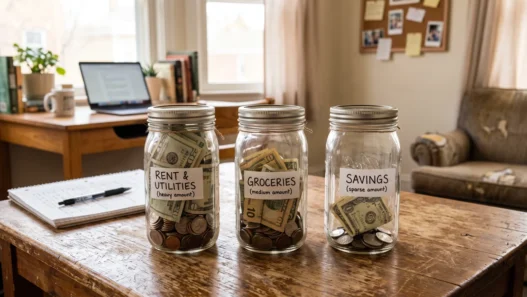
- 50% — Needs. The non-negotiables: rent, groceries, utilities, transport, phone bill, insurance, minimum debt payments. If you’d suffer real consequences for skipping it, it’s a need.
- 30% — Wants. The fun stuff: eating out, streaming subscriptions, clothes you don’t strictly need, concerts, gaming. This bucket exists on purpose — a budget with zero fun is a budget you’ll abandon by week two.
- 20% — Savings and extra debt payments. Emergency fund, future goals, and anything above the minimum on debts. Pay yourself first: move this money the day income arrives, before you can spend it.
That’s the whole system. The genius is that it’s proportional, not fixed — it scales whether you live on $800 or $3,000 a month.
A Worked Example: $1,600 a Month
Let’s say you’re a student working part-time, bringing home $1,600/month. Here’s your 50/30/20 split:
- Needs (50%): $800 — say $550 rent (with roommates), $150 groceries, $60 transport pass, $40 phone bill.
- Wants (30%): $480 — eating out, a streaming service or two, clothes, going out with friends.
- Savings (20%): $320 — straight into a separate savings account on payday.
Notice what happens with that $320: after one year, you’ve saved $3,840 without ever “feeling” like you were sacrificing. That’s an emergency fund, a plane ticket home, or a very comfortable cushion for post-graduation job hunting.
And the $480 in wants? That’s about $16 a day of guilt-free spending. The rule doesn’t judge what you spend it on — it just caps the total. Boba every day or one great dinner a week: your call.
But My Rent Alone Is 60%…
Fair. In expensive cities, the 50% needs target can be genuinely impossible for students. The rule is a compass, not a cage. If your needs run at 60–65%, adjust the other two buckets proportionally — maybe 60/25/15 for now. The point is the habit of splitting income deliberately, not hitting exact numbers.
Two things matter more than the precise ratio:
- Never let savings drop to zero. Even 5% saved consistently beats 20% saved “someday.” The habit compounds; the percentage can grow later.
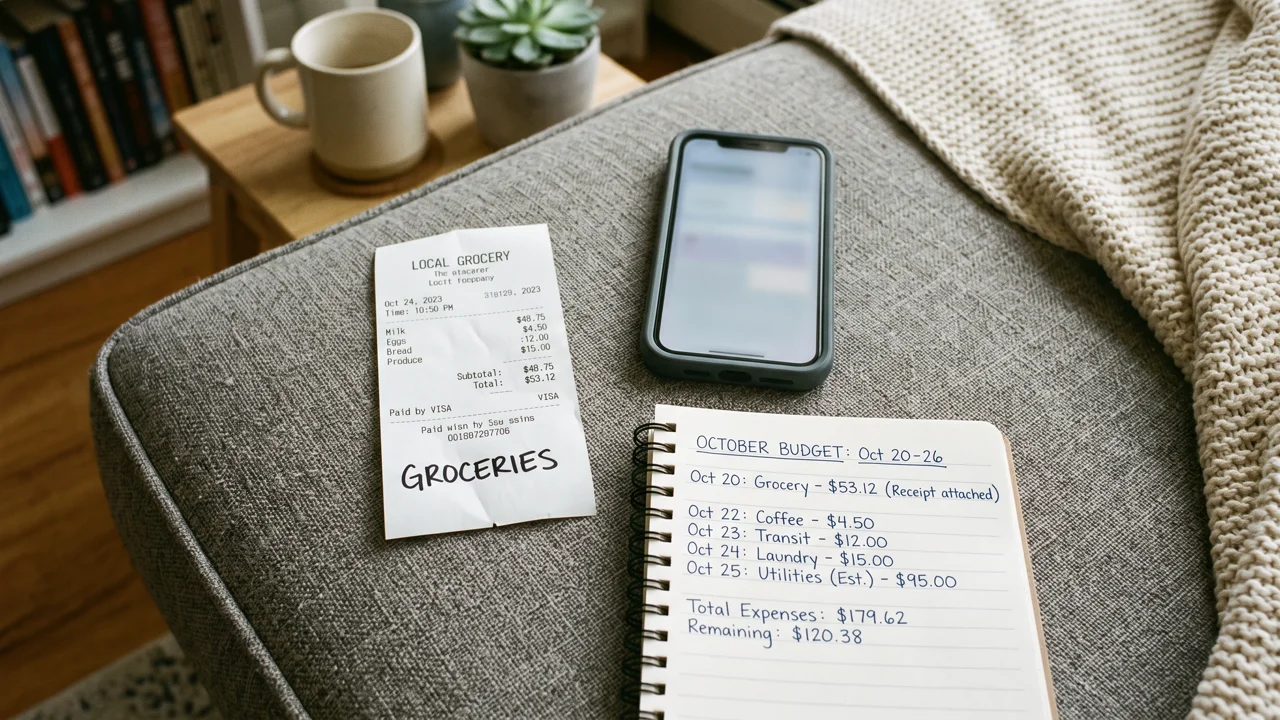
- Track for one month. You can’t fix what you can’t see. One month of honestly logging spending (a notes app is fine) usually reveals one or two leaks — the subscription you forgot, the daily $6 coffee — that free up real money.
- Give every dollar a job before the month starts. This is called zero-based budgeting, and it pairs perfectly with 50/30/20: instead of wondering where money went, you decide where it goes. The buckets are the plan; the tracking just confirms you followed it.
Student-Specific Tweaks
- Irregular income? Budget from your lowest typical month, not your best. In flush months, the surplus goes straight to savings.
- Textbooks and big semester costs: Divide them by the months of the semester and treat them as a monthly “need.” A $400 semester of books is ~$100/month — much less shocking than a surprise $400.
- Separate your savings physically. A different account — ideally at a different bank, without a debit card attached — makes “borrowing” from savings just annoying enough to prevent.
- Automate everything. Auto-transfer savings on payday. Auto-pay fixed bills. The less willpower your budget requires, the longer it survives.
Needs vs. Wants: The Tricky Calls
The system lives or dies on honest labeling. Some examples students get wrong:
- Gym membership: usually a want — unless it’s the only exercise keeping you functional, in which case it’s a cheap health need.
- Laptop repairs: need (it’s a school tool). A laptop upgrade you don’t strictly require: want.
- Coffee with friends: want — but social connection matters, so budget for it deliberately instead of pretending it’ll be zero.
- Subscriptions: audit them ruthlessly. Three streaming services you barely watch is a classic student money leak.
When in doubt, ask: “Would skipping this for a month cause real harm?” If yes, it’s a need. If it just causes FOMO, it’s a want.
Common Traps to Watch For
- Lifestyle creep with every raise. Got a better-paying shift? Great — keep living on the old budget for one more month and bank the difference.
- “It’s only $10.” Ten dollars three times a week is $120 a month — nearly 8% of a $1,600 budget. Small leaks sink budgets.
- Confusing wants with needs. The $80 sneakers you need for the gym? Need-ish. The $180 limited drop? Want. Be honest with yourself; the budget only works if the labels are true.
- All-or-nothing thinking. Blew the budget in week three? The month isn’t ruined — just tighten up week four. Budgets are steering wheels, not report cards.
Why This Matters More Than You Think
Money stress doesn’t stay in the money corner of your life. Research consistently links financial stress to worse sleep, worse grades, and worse mental health. A simple system like 50/30/20 won’t make you rich, but it converts vague money anxiety into a concrete plan — and concrete plans are something your brain can actually relax about.
Start this week: calculate your monthly income, split it into the three buckets, and set up one automatic savings transfer. Twenty minutes of setup, and you’ll be ahead of most adults. Not bad for a Wednesday.
And if you’re thinking about turning what you’re learning into income down the road, check out how to turn course certificates into a paycheck — and before spending on any course, read when it’s actually worth opening your wallet versus learning for free.